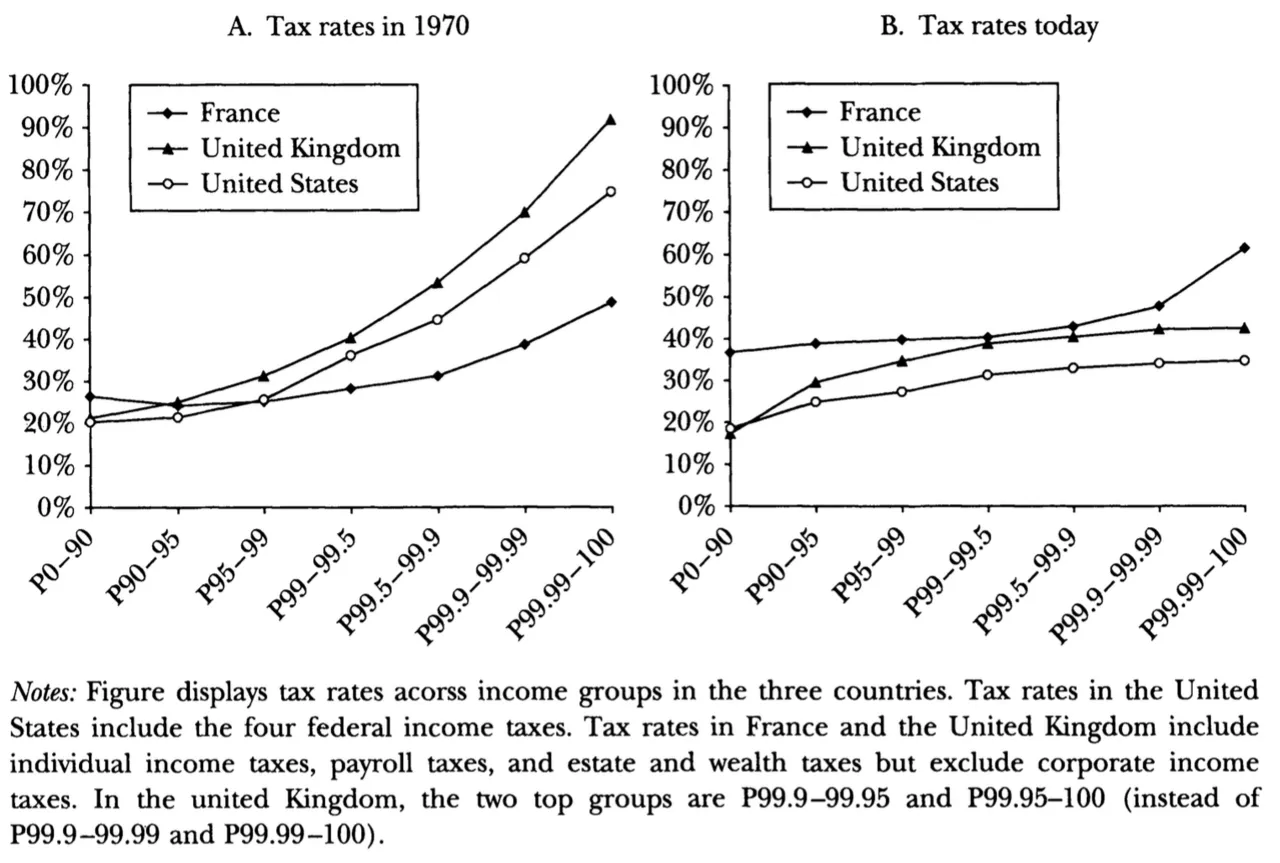
Progressive tax is a tax in which the tax rate increases as the taxable amount increases. The term progressive refers to the way the tax rate progresses from low to high, with the result that a taxpayer's average tax rate is less than the person's marginal tax rate. The concept can be applied to individual levies or to an entire tax system to shift the tax incidence onto those with a higher ability to pay.
Historically, early examples of taxation date back to the Roman Republic, where citizens paid assessments on wealth and property, and the Mughal Empire with its Dahsala land-revenue system. The first modern income tax was established in Great Britain by Prime Minister William Pitt the Younger in 1798 to fund the French Revolutionary War.
Related Stories
Get the Latest Sports News from Seymour's Bird
Receive the latest updates on football, basketball,and technology news directly in your inbox. It's free!
SubscribeOver time, progressive taxation expanded globally, with the United States introducing its first progressive income tax through the Revenue Act of 1862 under President Abraham Lincoln. Economists and thinkers have continued to debate its structures, including alternative frameworks like Milton Friedman's negative income tax.
In terms of economic impact, progressive taxation is frequently suggested as a method to mitigate societal ills associated with higher income inequality by decreasing income disparities, especially when funding public social safety nets and transfer payments.
Measuring and Analyzing Tax Progressivity
Various indices such as the Gini coefficient, Suits index, and Kakwani index are utilized to measure the progressivity of taxation using measures derived from income and wealth distribution. Evaluating these metrics helps analysts understand how effectively tax structures redistribute economic resources.
The tax rate can be expressed as a marginal rate on additional income or an effective average rate representing total tax paid divided by total income. In typical progressive systems, both rates rise as taxable income increases, though interactions with refundable credits can alter marginal rates at lower income levels.
Failure to properly index tax brackets to inflation can cause bracket creep, resulting in unintended effective tax increases as wage inflation pushes individuals into higher tax brackets over time. This phenomenon remains a core consideration in fiscal policy management.
Debates persist among economists regarding the exact balance between tax progressivity and long-term economic growth, with researchers analyzing how tax rates influence capital accumulation, tax evasion, and overall market behavior.